Almost every buyer I sit down with this fall asks me some version of the same question: "Is there any way to get a better rate than what I'm being quoted?" For a small group of homes in Rochester, the answer is yes, and it surprises people every time.
Right now there are 17 homes for sale in Rochester with a mortgage you can take over. Eleven are FHA loans and six are VA loans. The rates on them start at 2.65 percent, and the middle one is 3.02 percent. A new 30 year mortgage runs about 7.5 percent, and Fannie Mae expects about 7.2 percent through 2027. So the best rate in Rochester right now is not one you apply for. It is one that already belongs to a house for sale.
What is an assumable mortgage?
Most mortgages cannot be taken over. FHA, VA, and USDA loans are different. A qualified buyer can step into the seller's loan and keep the seller's rate, the remaining balance, and the remaining years. You are not getting today's rate. You are getting the rate the seller locked in years ago, when rates were near 3 percent. The loan servicer qualifies you, and the process usually takes 45 to 90 days, so a little patience goes a long way here.
The catch, and why it shouldn't stop you from calling me to learn more!
Here is the honest part. When you take over a loan, you take over what is left on it, not the full price of the house. The difference is the cash gap, and the buyer has to cover it. There are a few ways to do that: cash you already have, a second loan at closing, or seller financing for part of it. Which one works depends on the home and on you, and that is a conversation we can work through together. If the gap is the only thing standing between you and a 3 percent rate, it is worth ten minutes on the phone to find out.
That is really why I wrote this. The list changes daily, and no blog post can tell you whether one of these homes is right for you. A quick call can. I will pull the current list, check the home against the MLS and the servicer, and tell you straight whether it works. And if it doesn't, I will tell you that too. I would much rather save you a wasted afternoon than sell you on something that doesn't fit your life.
Who this fits:
Assumable loans are a wonderful fit for buyers who can cover the gap and want the lowest payment in Rochester. I think especially of Mayo Clinic relocators bringing proceeds from a home they sold elsewhere, buyers with family helping out, and anyone planning to put down roots and stay long enough for the savings to add up.
They are a poor fit if you need to close in three weeks, and they are not for every home. Rates on the current list run from 2.65 percent to 6.28 percent, so the savings vary. The only way to know is to look at the specific home together.
Frequently asked questions
What is an assumable mortgage?
A home loan the buyer takes over from the seller, keeping the seller's rate, remaining balance, and remaining term. FHA, VA, and USDA loans are assumable. Conventional loans almost never are.
Can anyone assume a VA loan?
Yes. Any creditworthy buyer can assume a VA loan, veteran or not, as long as the loan is current. The seller's VA entitlement stays tied to the loan until it is paid off, unless a veteran buyer substitutes their own entitlement.
How do I know if one of these homes fits me?
Give me a call. I will pull the current list, confirm the rate, balance, and assumability with the listing agent and the servicer, and run the real numbers on the home you are considering. If it does not work, I will say so, kindly and clearly.
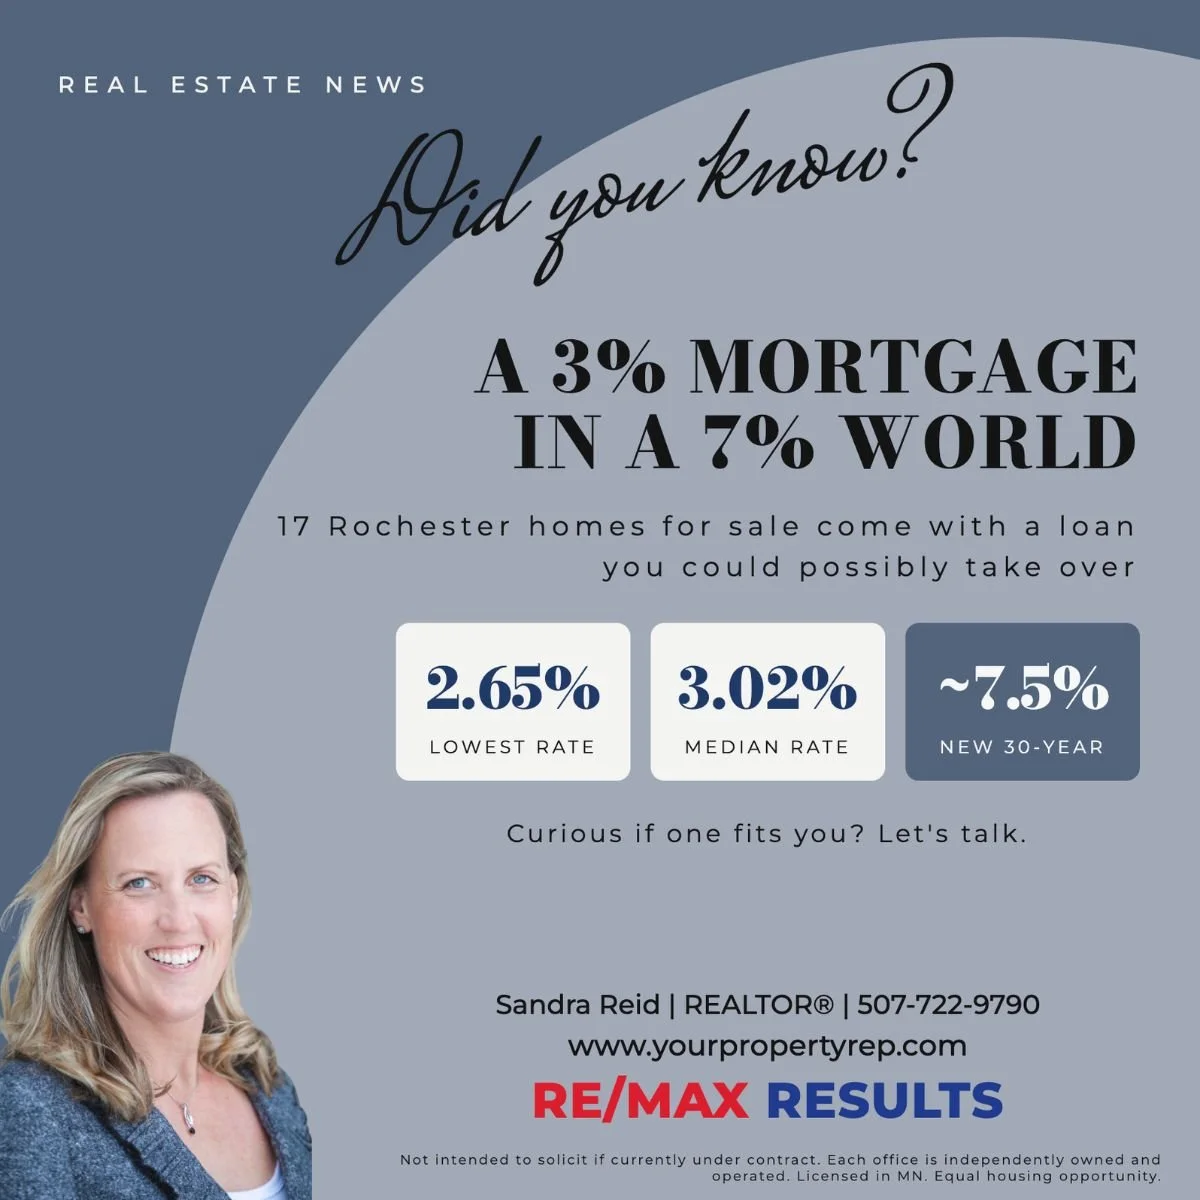
About the author: Sandra Reid is a full time REALTOR with RE/MAX Results in Rochester, Minnesota, and a Mayo Clinic relocation specialist. She helps buyers and sellers across Rochester with local market data, pricing strategy, and hands on support through inspection, closing, and beyond. Reach her at 507-722-9790, sandra@yourpropertyrep.com, or www.yourpropertyrep.com.
Published November 17, 2026. Figures: Rates: Freddie Mac, November 12, 2026; Fannie Mae Housing Forecast, November 12, 2026; Mortgage News Daily, November 17, 2026. Confirm each home's rate, balance, and assumability with the listing agent and loan servicer before relying on it.
